California wildfire insurance
Got a Wildfire Non-Renewal Notice? How to Keep Your Insurer
That letter is not a verdict. It's a deadline.
What to Do Next
- Don't panic, and don't cancel anything.Find two things on the letter: the date your policy ends and the reason.
- Ask your insurer what to fix.Email them: "What specific items on my property led to this, and will you reconsider if I fix them before my renewal date?" Ask for any photos they used.
- Call your broker this week.Ask them to back up your request, and to quietly start shopping in case you need a plan B.
- Fix the first 5 feet around your house.That's where insurers look first (see below).
- Send proof before your renewal date.Before and after photos plus invoices, sent to your insurer and broker with a request to renew. If they still say no after you fixed what they asked, call the California Department of Insurance at 800-927-4357.
What Insurers Look For First
Most wildfire non-renewals we see come down to what's touching the house.
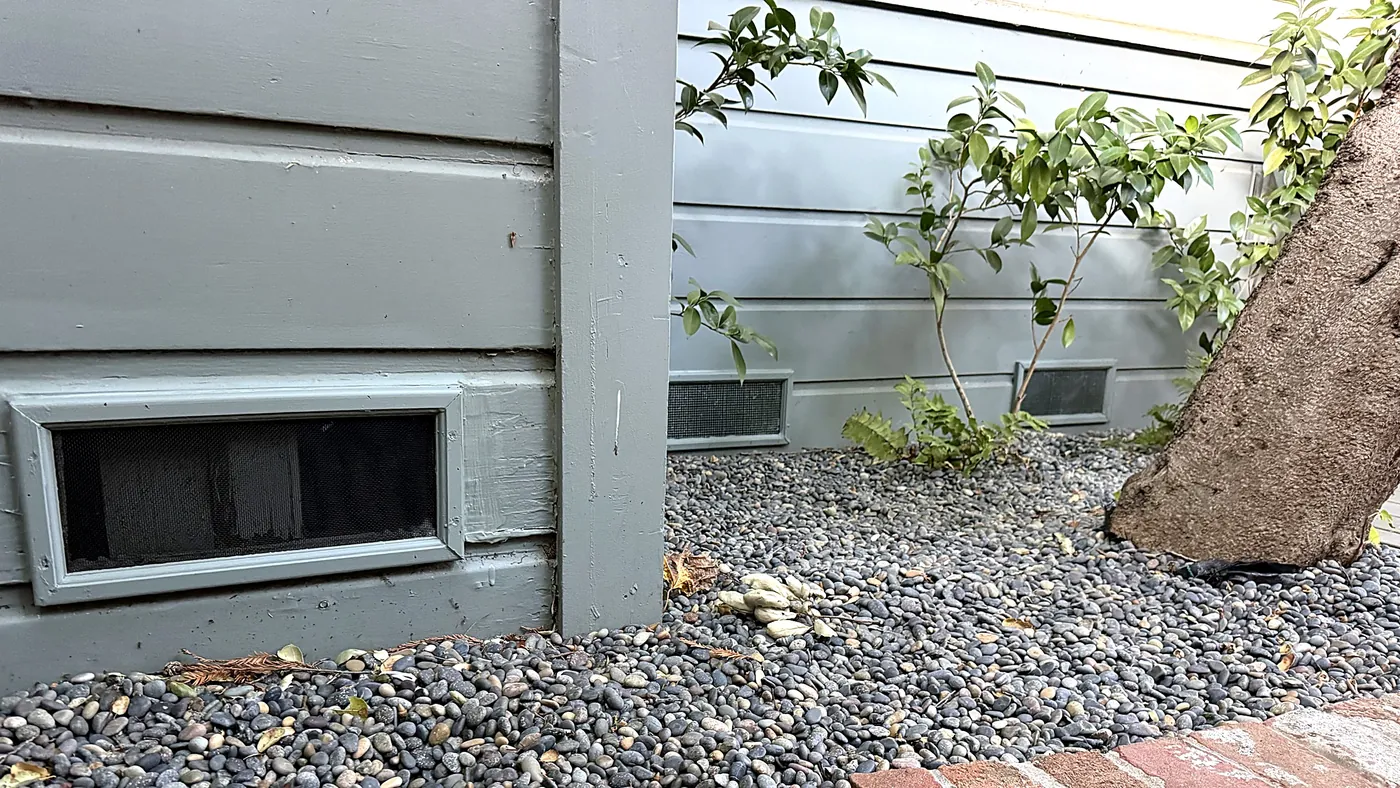
- Bark mulch or wood chips against the house. Swap them for river rock or gravel.
- Wood fences that touch the house or sit within 5 feet of it. Remove or replace with metal.
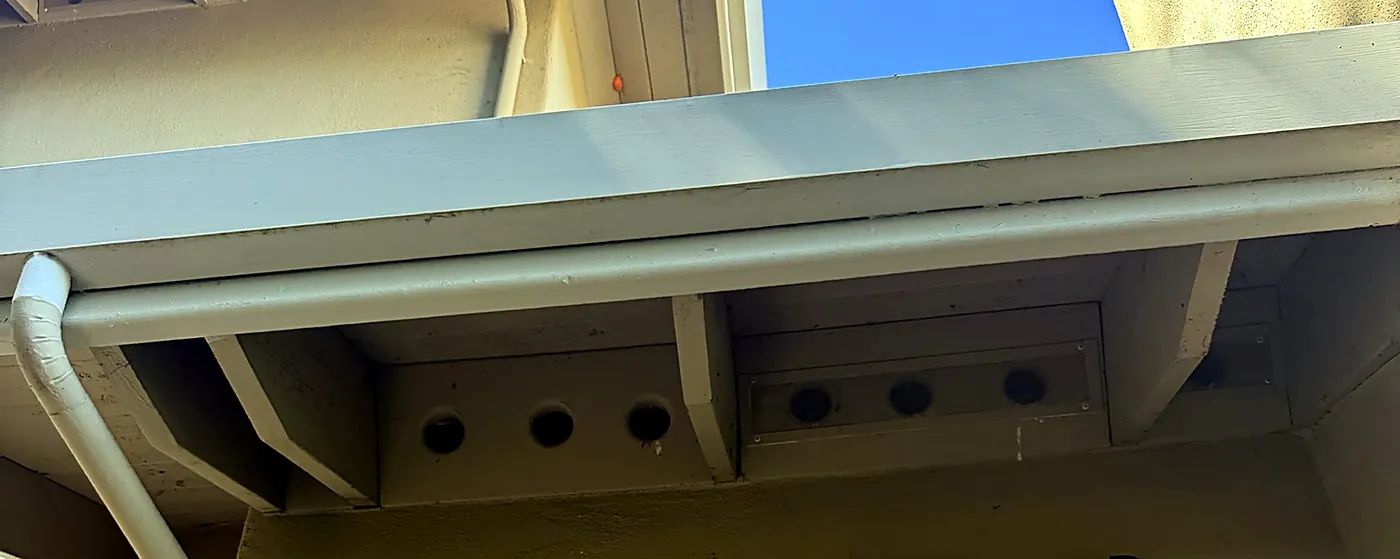
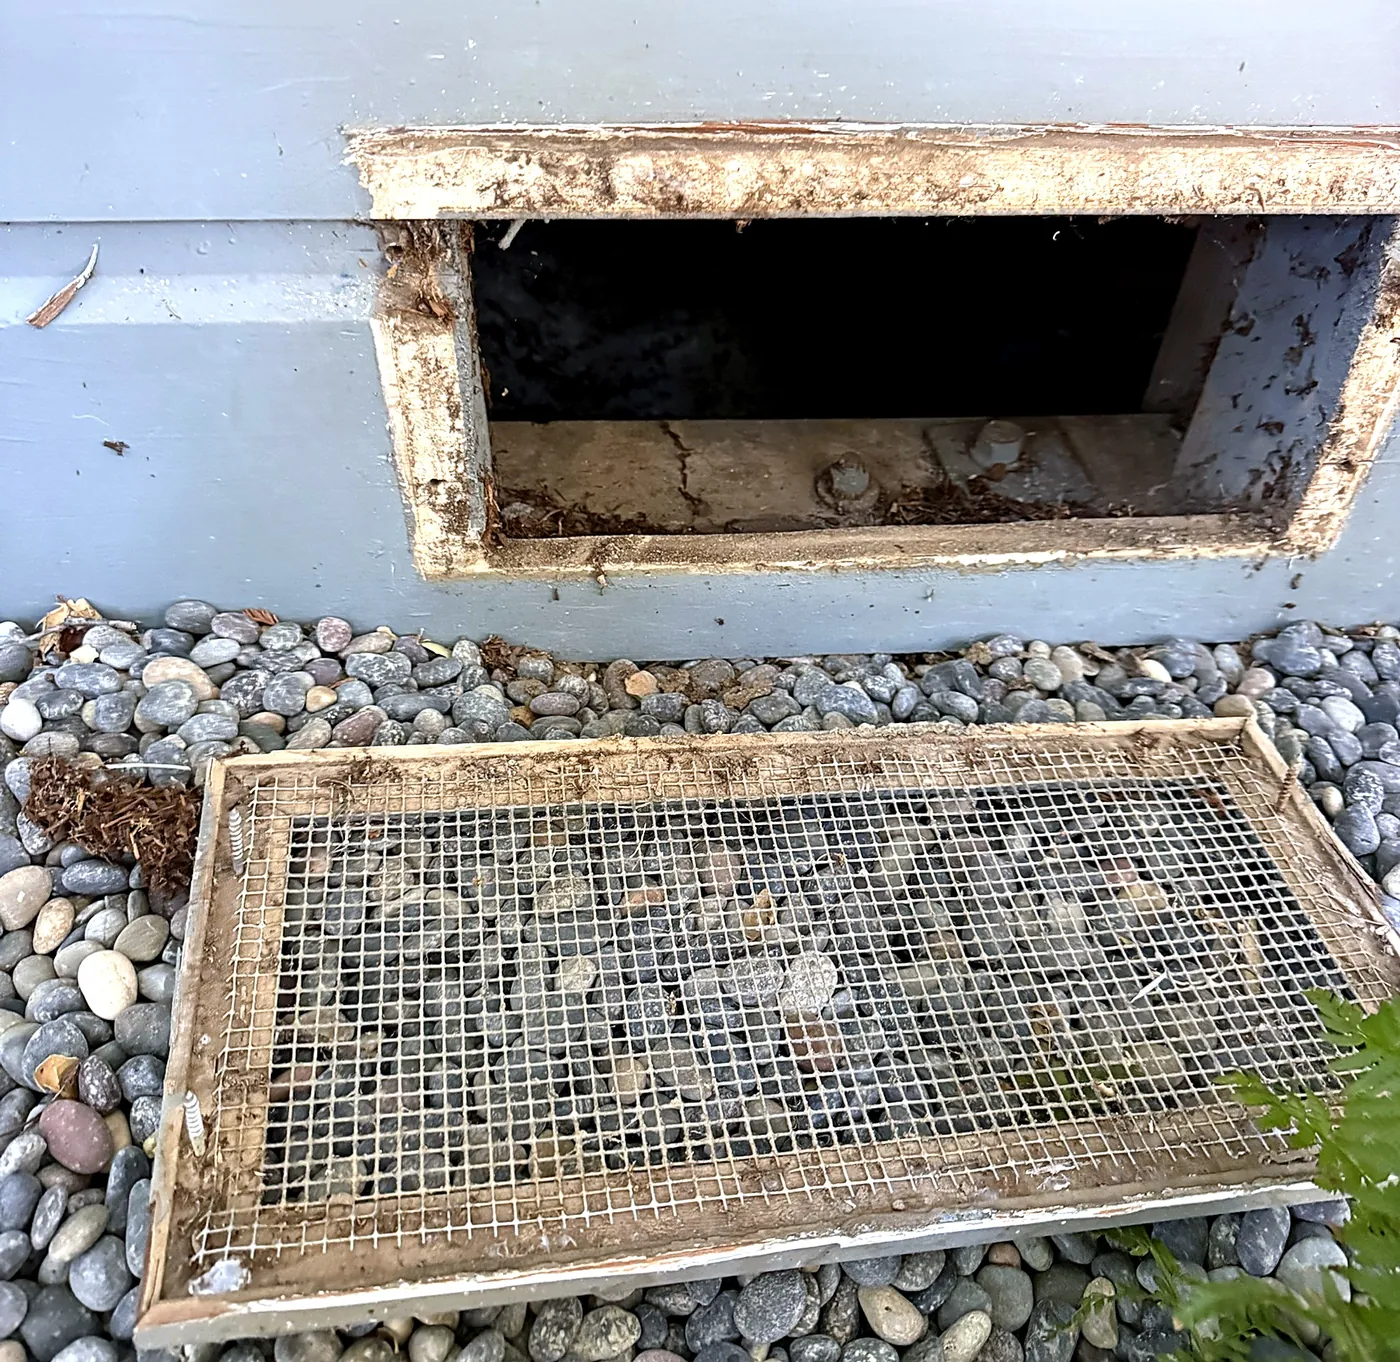
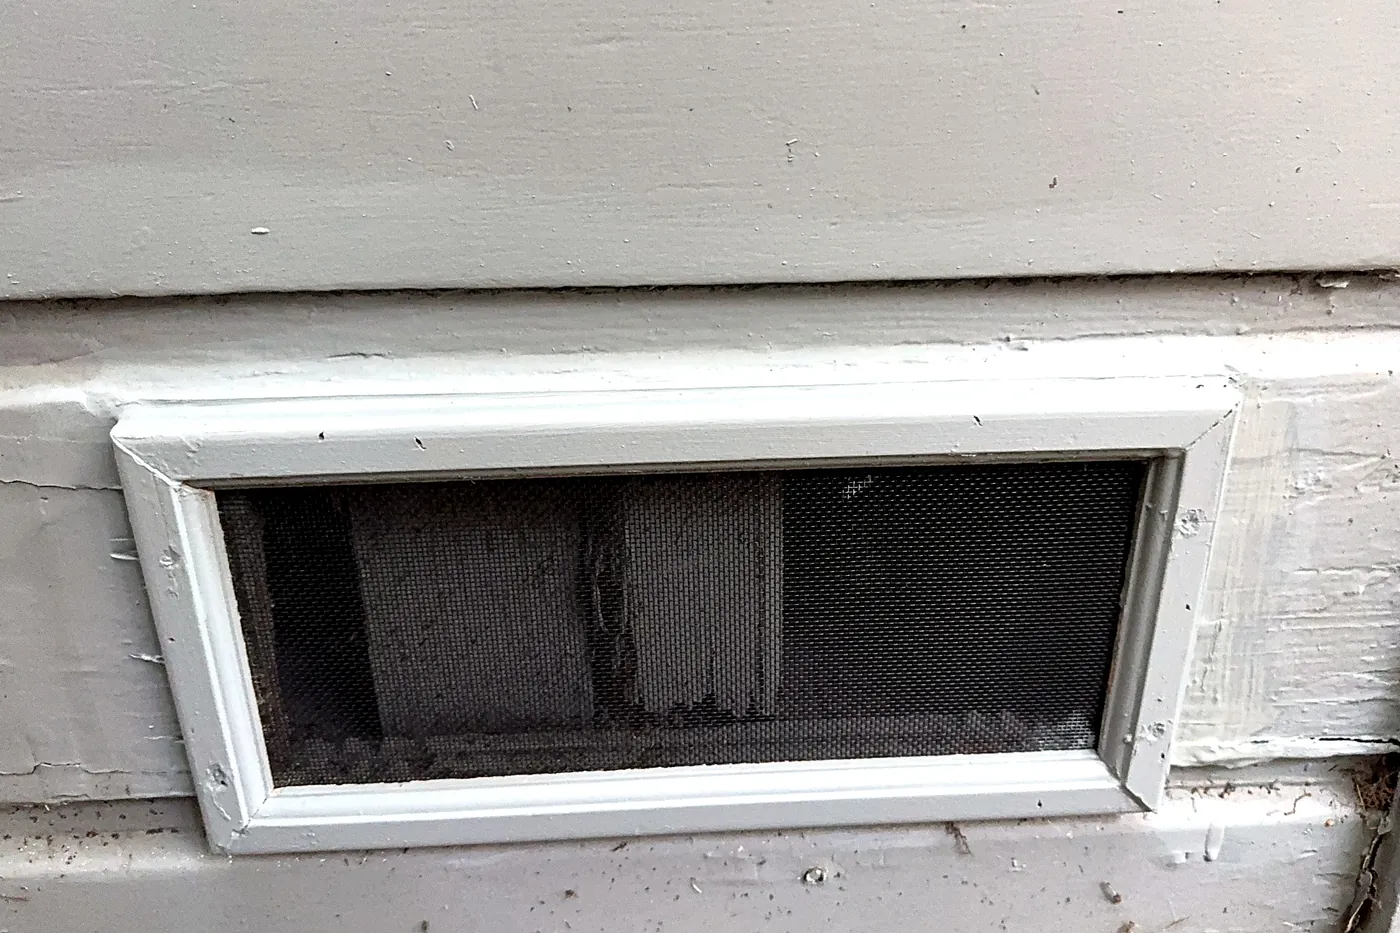
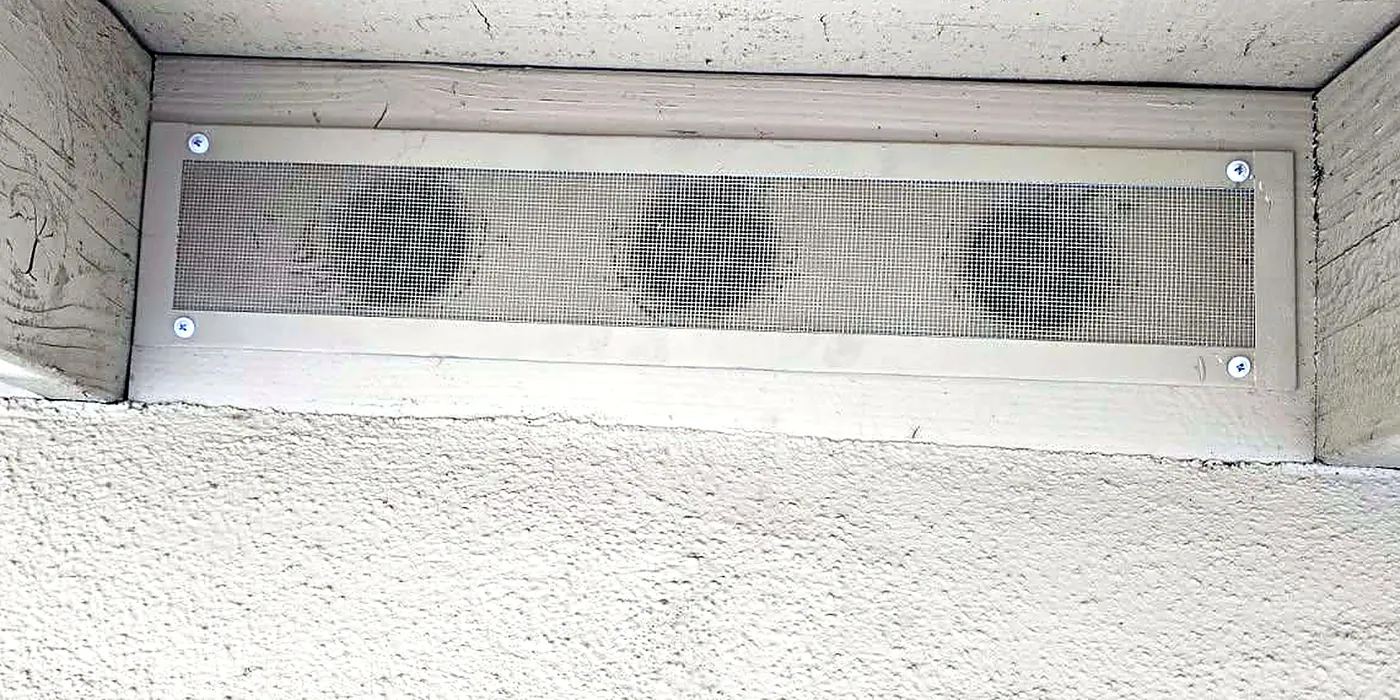
- Old or open vents. Foundation, attic and soffit vents need fine ember-resistant mesh.
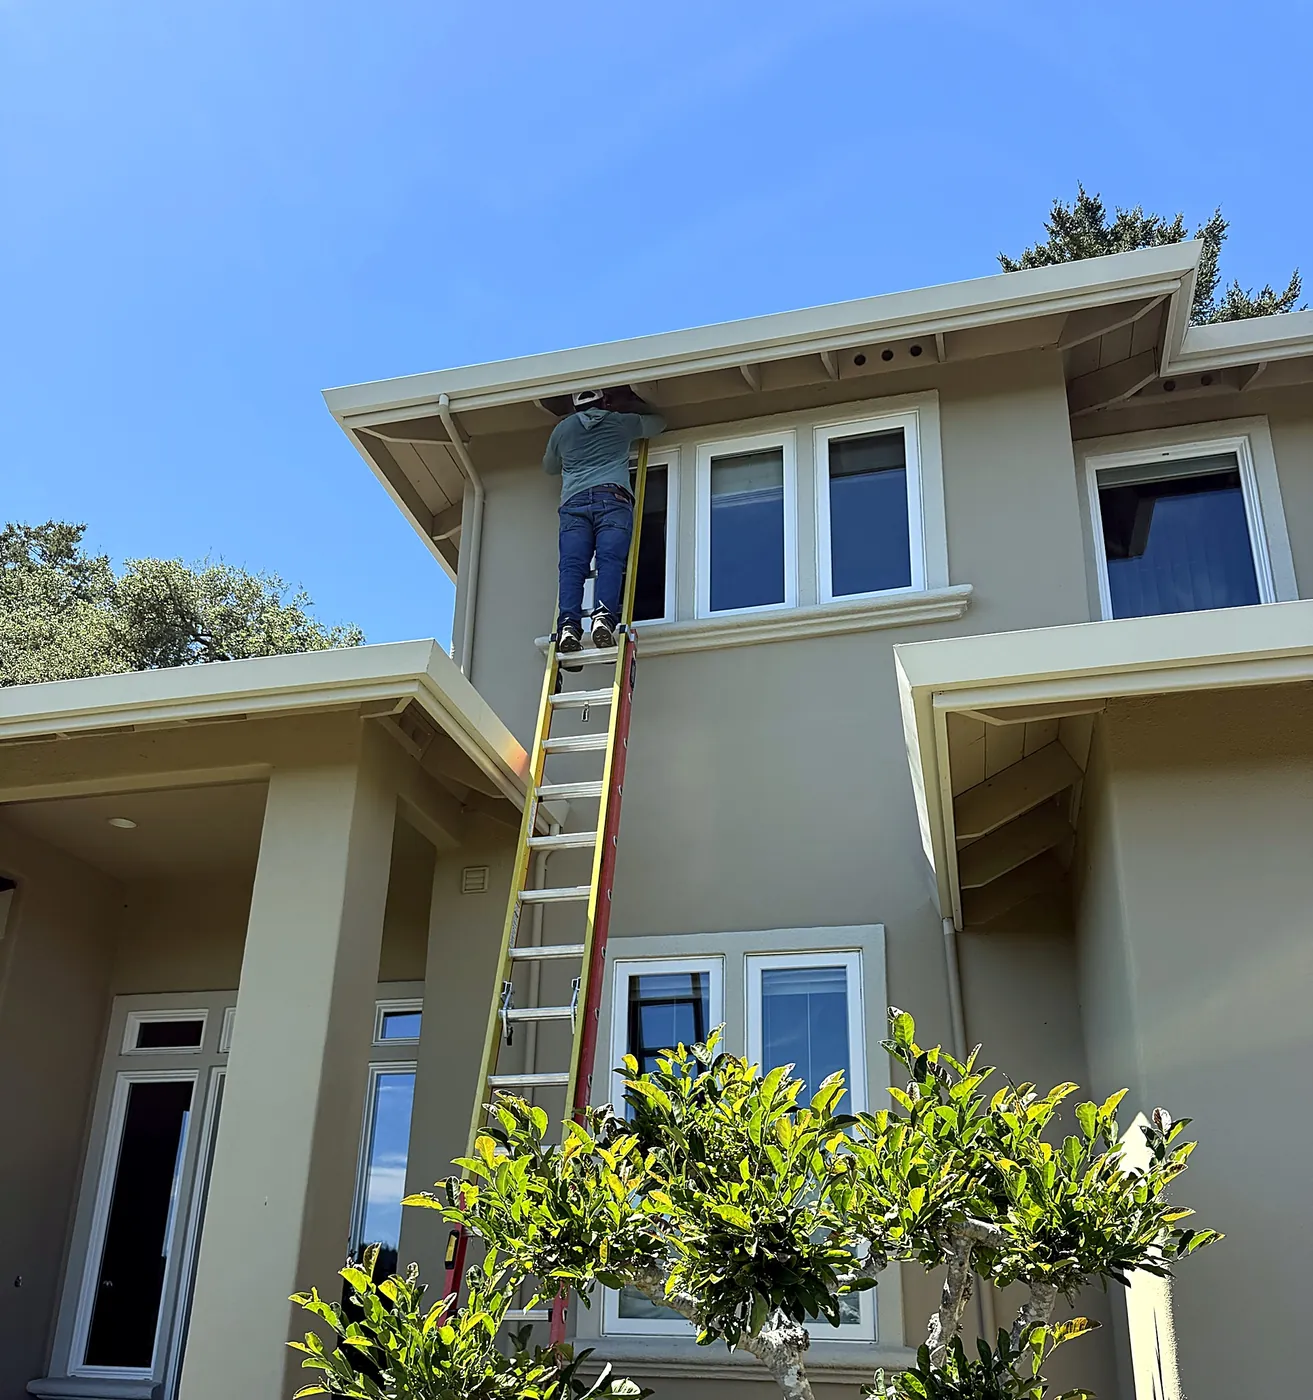
- Open eaves. Enclose them so embers can't collect under the roof.
- Leaves and needles on the roof and in gutters. Keep them clear.
It works
Scotts Valley
We helped a homeowner insured with USAA keep their policy. We cleared the first 5 feet, replaced mulch with river rock, retrofitted the foundation and soffit vents, and removed wood fencing near the house.
Los Gatos
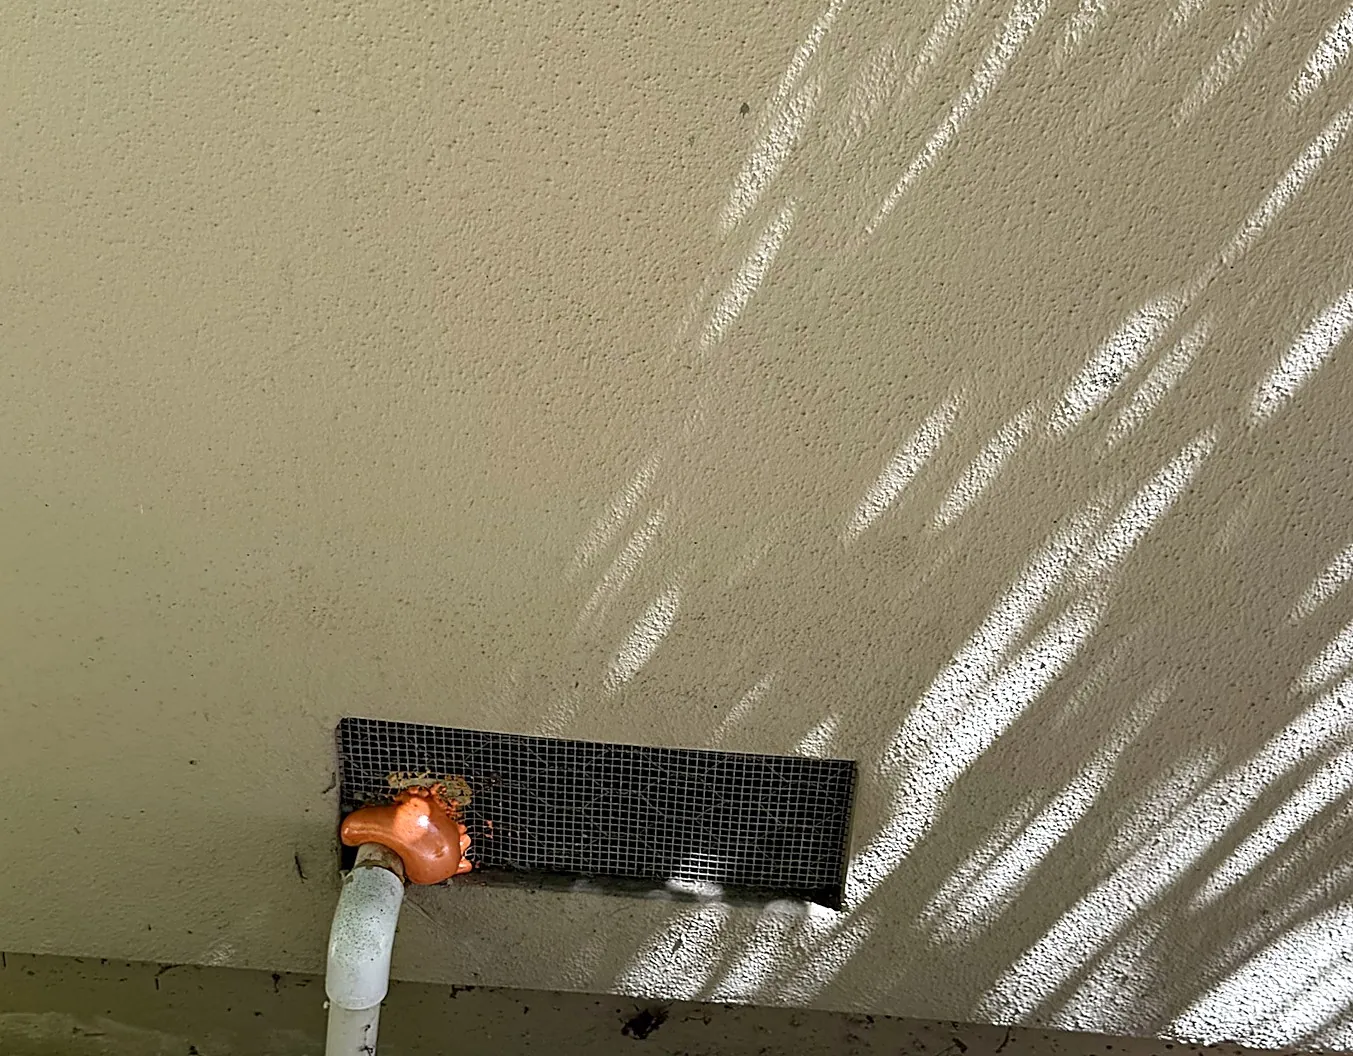
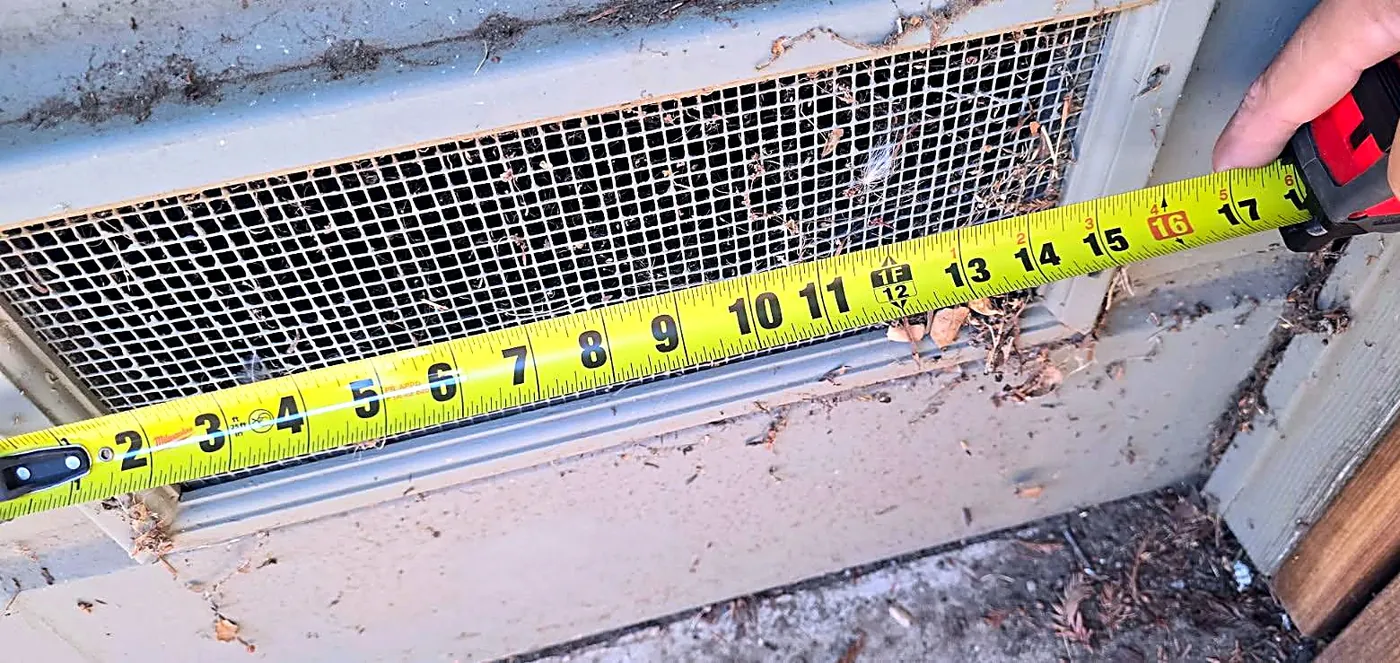
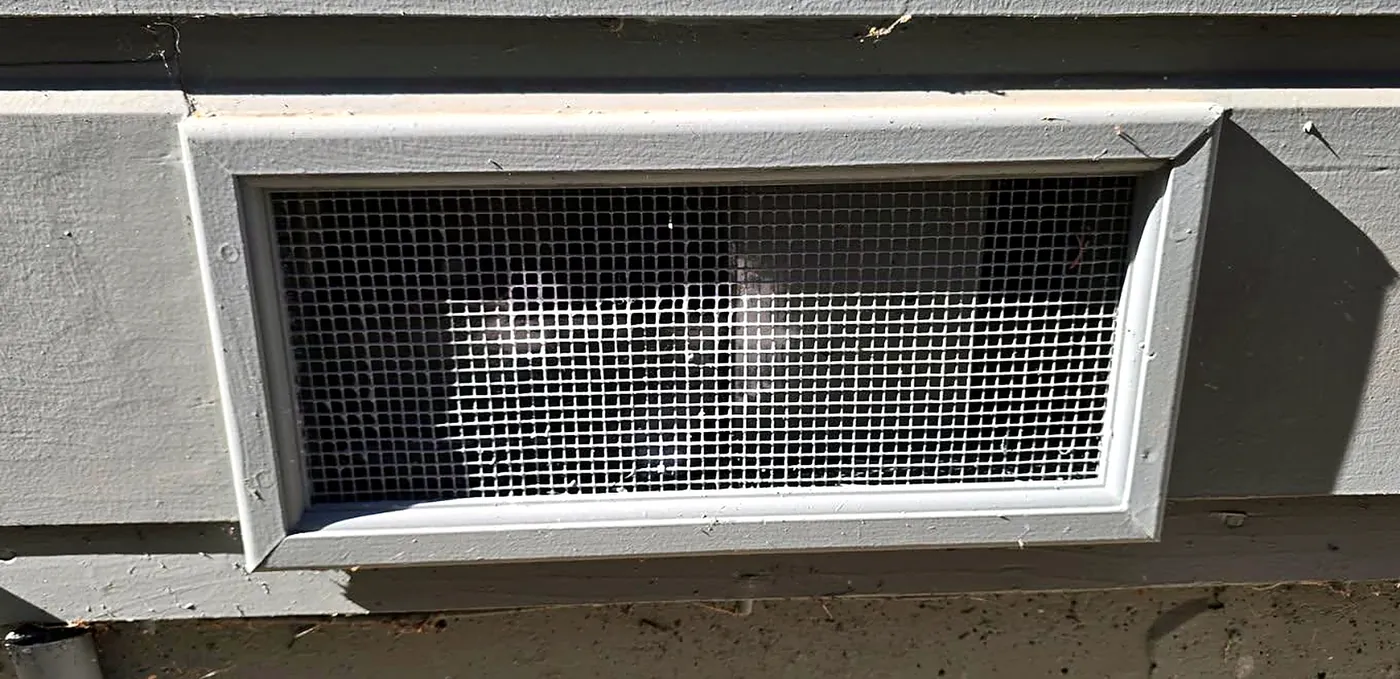
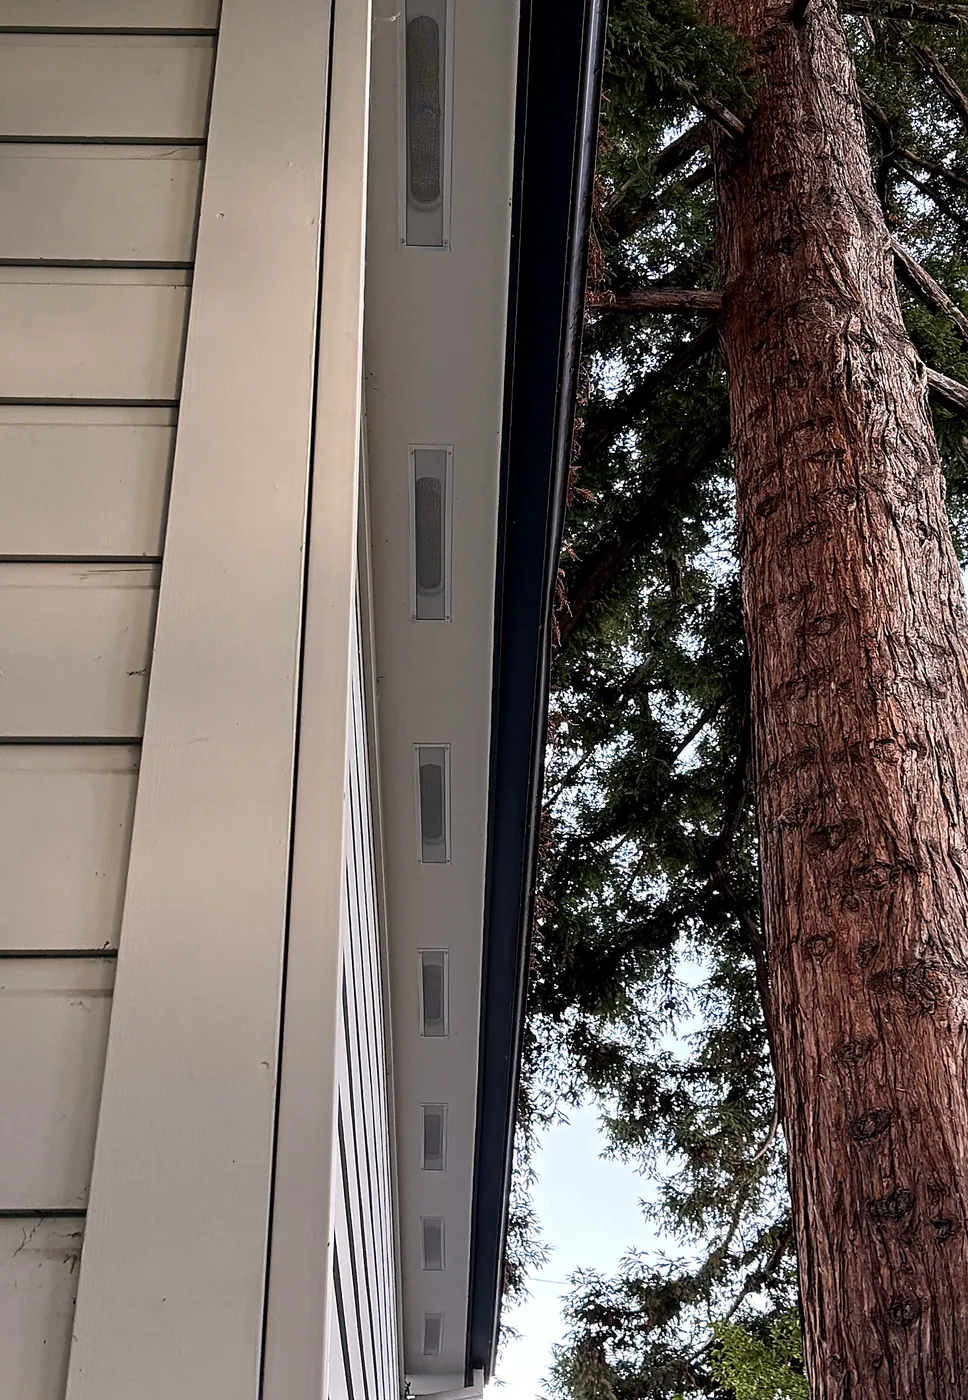
We treated 33 openings on a PURE-insured home in September 2026: 21 soffit vents, 11 crawlspace vents and a 6-foot channel vent, each screened with fine ember-resistant mesh and painted to match.
Portola Valley
We screened 10 gable and crawlspace openings on a FAIR Plan home with 1/8-inch stainless steel mesh, sealed every edge with fire-rated caulk, and documented it for the homeowner's FAIR Plan discount.
Every one of them got a documentation package their broker sent straight to the carrier.
It's not just our clients. Another Portola Valley homeowner got a non-renewal, hardened the home to the Wildfire Prepared Home standard, and was reinstated.
Don't Get Stuck on the FAIR Plan
The FAIR Plan is California's insurer of last resort. It's there so no one goes uninsured, but it's a step down:
- It covers fire and smoke only. You'll need a second policy for theft, water damage and liability.
- It caps coverage at about $3 million. We work with FAIR Plan homeowners whose homes are worth more than $4 million, so part of their home has no coverage at all. For them, active defense matters even more: automated exterior wildfire sprinklers plus home hardening protect what the policy can't.
- Its rates just went up an average of 29% in October 2026.
Already on it? Shop at every renewal, ask your broker which insurers are writing in your ZIP code, and keep hardening your home. It's the same work that gets private insurers to say yes.
Insurers Are Rewarding Hardened Homes
Several major insurers now favor homes with the Wildfire Prepared Home designation from IBHS, a nonprofit backed by the insurance industry. Some will renew those homes for years at a time, and others are reopening to new customers only if the home has it. It starts with the same list above: vents, the first 5 feet, fencing, roof and gutters.
How FireRoofs Helps
- We walk your property the way an insurer looks at it and tell you what to fix first.
- We do the work: vents, soffits, Zone 0 cleanup and fencing, built by a FireRoofs Vetted Installer.
- We handle the paperwork: photos and a summary your broker and insurer can approve fast.
- Want more protection? Ask about automated exterior wildfire sprinklers.
Common Questions
- How much time do I have?
- At least 75 days from when the letter was mailed. Start this week.
- Can a non-renewal be reversed?
- Often, yes, if you fix what your insurer flagged and send proof before the renewal date.
- Does hardening guarantee I keep my policy?
- No, but it's the best move you have and what insurers are rewarding.
- Do exterior sprinklers lower my insurance?
- No. However, homes on the California FAIR Plan valued over $3 million are choosing automated exterior wildfire sprinklers to protect their investment, because the FAIR Plan caps coverage at $3 million.
Your letter has a date on it. Let's use the time.
General information, not legal or insurance advice. Confirm details with your broker.